A funding round may close in a day. The relationship it creates can shape every major decision that follows. Founders should therefore diligence investors, governance and alignment as rigorously as investors diligence the company.
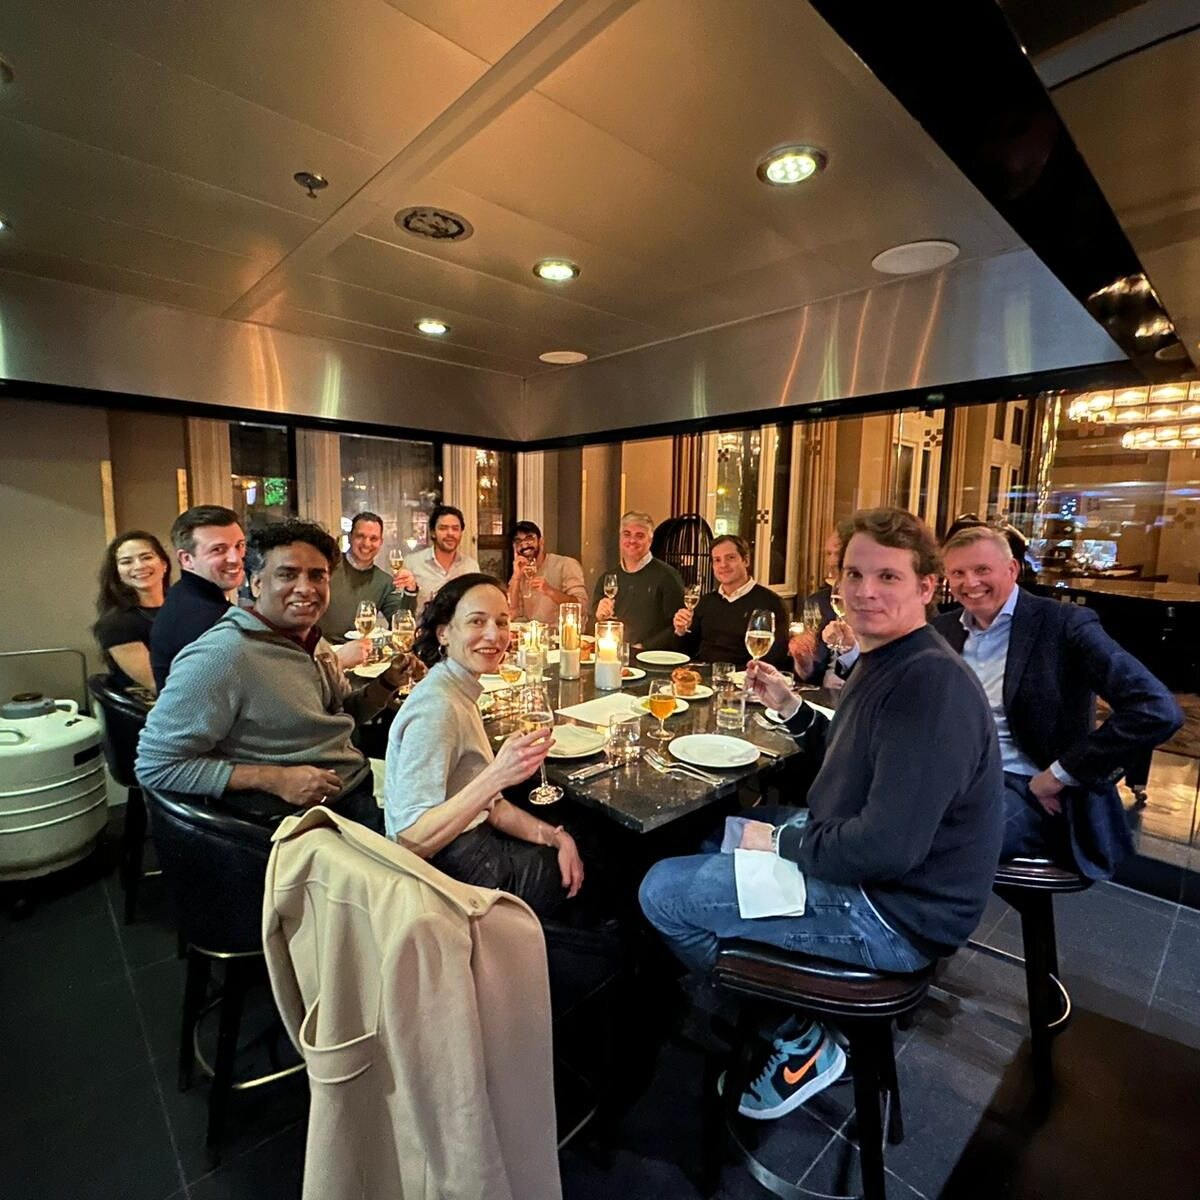
This photograph was taken at the closing dinner of Soly's Series B. It captures what every founder recognises: the relief after a demanding process, pride in the team and the feeling that a new chapter can finally begin.
Before that dinner came months of planning, presentations, due diligence, negotiation and legal work. The company was examined from almost every angle: market, financials, technology, commercial performance, team, risks and forecasts.
That asymmetry is normal. Investors put capital at risk and need to understand the company. But founders often spend so much energy proving that the company is investable that they do not investigate the other side with the same discipline.
The closing is then treated as the finish line. In reality, it is the moment the most consequential part begins.
Capital changes more than the bank balance
Institutional capital can accelerate a company enormously. It can fund product development, international expansion, acquisitions, leadership hires and the systems required for scale. It can also strengthen credibility and give a company room to pursue opportunities that bootstrapping cannot support.
But the company changes in return. New shareholders bring mandates, time horizons, decision processes and expectations. The board changes. Information requirements increase. Certain decisions move from founder discretion to collective approval. Strategy is no longer only a management question; it becomes a governance question.
None of that is inherently negative. Professional governance can make a company stronger. The risk begins when founders understand the valuation and funding amount—but not the operating reality of the relationship they have entered.
Investor due diligence should work both ways
1. Study behaviour under pressure
References from successful portfolio companies are useful, but incomplete. The most valuable conversations are with founders whose company missed a budget, needed bridge funding, faced a down round, changed leadership or explored an unexpected exit.
Ask what happened when the board disagreed. How quickly did the investor make decisions? Did they help create options or mainly protect their own position? Behaviour when everything is going well tells you very little about the relationship you may eventually need.
2. Understand the mandate behind the person
A good relationship with an individual partner matters, but that person operates inside a fund. Founders should understand the fund's time horizon, investment stage, follow-on capacity, ownership targets, internal approval process and portfolio construction.
The person across the table may support a plan while their investment committee, fund life or mandate creates different constraints. Alignment needs to exist at both levels.
3. Discuss the difficult scenarios before signing
Most funding conversations focus on the upside case. Governance is tested in the downside and deviation cases: the next round takes longer, a market misses plan, the company needs to reduce costs, an acquisition opportunity appears, a strategic buyer makes an offer or the CEO role needs to change.
Do not wait until one of those situations occurs. Discuss who decides, what information is required, how quickly the board can act and what each shareholder is likely to optimise for.
4. Test the claimed value-add
Almost every investor offers a network, strategic support and access to talent. Make that promise concrete. Who would actually help with your next two leadership hires? Which market-entry experience is available? How many portfolio boards does the partner already serve? What happened the last time a company needed intensive support?
A logo on the cap table can create credibility. It is not the same as operating capacity when the company needs help.
5. Evaluate board quality—not only investor quality
A board should be more than a reporting audience. It needs the right mix of independence, operating experience, financial discipline and willingness to challenge. The chair matters. The information flow matters. The distinction between supervision and management matters.
Good governance helps founders see around corners. Poor governance adds process without improving decisions.
Do not outsource understanding the deal
Founders need strong legal and financial advisors. Complex documents demand specialist expertise. But advisors cannot decide which balance of control, protection and flexibility is right for the founder and the company.
I would now insist on three simple founder-owned documents alongside the legal agreements:
- A decision map. Which choices remain with management, which require the board and which require shareholder approval?
- A scenario model. What happens to ownership, economics and decision power in the base case, a delayed round, a down round and an exit?
- An alignment memo. What does each shareholder want, over what time horizon and where could those interests diverge?
If a founder cannot explain the governance in plain language, the work is not finished. The objective is not to become a lawyer. It is to understand how the company will actually be governed when decisions become difficult.
Governance is an operating system
Governance is often experienced as paperwork: board packs, approvals, minutes and reserved decisions. At its best, it is the operating system connecting strategy, cash, risk, management and shareholders.
That system needs reliable inputs. A board cannot protect the company with delayed reporting, inconsistent KPIs or an optimistic cash forecast. Management cannot move at speed if decision rights are unclear or every deviation triggers a negotiation about process.
Strong governance therefore starts before the board meeting: one version of the numbers, a forward-looking cash view, clear ownership of actions and enough context to distinguish a temporary miss from a structural change.
It also requires honest human behaviour. Data can inform a decision, but trust determines whether uncomfortable information reaches the table early enough.
Eight questions I would ask before closing
- Which founders should I call who experienced a difficult period with this investor?
- What does this fund need to achieve—and by when?
- Who really makes follow-on and exceptional decisions?
- How will the board be composed, chaired and evaluated?
- Which decisions require approval, and can that process match the speed of the business?
- What happens if growth, funding or exit timing deviates materially from plan?
- Where are founder, investor and company interests naturally aligned—and where are they not?
- Would I still choose this partner if the next two years became harder than expected?
I look back at the dinner with pride. Closing an institutional round is a major achievement for any team. The lesson is not that founders should fear investors or avoid governance. It is that both deserve more founder attention before the champagne is opened.
The right capital, board and governance structure can make a company faster, more resilient and less dependent on the founder. But that outcome is not automatic. It is designed—through mutual diligence, explicit alignment and the courage to discuss the difficult scenarios while everyone is still optimistic.
Patrick van der Meulen
Founder & Operating Partner